
15 Retirement Planning Steps for Black Women Over 40 to Secure Your Future
Retirement planning for Black women over 40 deserves real attention right now. The years ahead can be your most secure yet, but only if you start making clear moves today. Many of us spent our 30s building careers and raising families. Retirement felt far away. Now it is closer, and the choices you make in…
Retirement planning for Black women over 40 deserves real attention right now. The years ahead can be your most secure yet, but only if you start making clear moves today.
Many of us spent our 30s building careers and raising families. Retirement felt far away. Now it is closer, and the choices you make in your 40s shape how comfortable your 60s and beyond will be. We publish practical guides like this one on TheFlawlessEdit.
This guide gives you 15 practical retirement planning steps for Black women over 40. No jargon, no scare tactics. Just clear actions you can take this year to build a future you can count on.
Your future self is counting on the decisions you make today.
Know Your Retirement Number
You need a target to aim for.

Estimate how much yearly income you will need in retirement. A common starting point is 70 to 80 percent of your current income. Multiply that by 25 for a rough savings target.
Use a free online retirement calculator to refine it. Plug in your age, savings, and expected retirement age.
Having a number makes everything else clearer. You will know if you are on track or need to catch up.
Max Out Catch Up Contributions After 50
Your 50s come with a savings bonus.
Once you turn 50, the IRS lets you contribute extra to 401k and IRA accounts. These catch up contributions can add thousands more per year.
In your 40s, prepare by increasing contributions now. Even 1 percent more each year adds up.
When 50 hits, take full advantage. It is one of the best tools for late starters. Combine these increases with simple saving money tips.
💡 Quick Tip
Increase your 401k contribution by 1 percent every year. You will barely notice it, but your future self will thank you.
Review Your 401k and IRA Options
Make sure your accounts work for you.
Check what type of accounts you have. A 401k through work, a Traditional IRA, a Roth IRA, each has different tax benefits.
If your employer matches 401k contributions, contribute at least enough to get the full match. That is free money.
Consider a Roth IRA for tax free growth. Talk to a tax pro about what fits your situation.
Missing employer match, wrong fund choices, paying high fees.
Full match captured, low fee funds, accounts working hard.
Pay Down High Interest Debt Before Retiring
Debt eats retirement savings.

Carrying high interest debt into retirement strains a fixed income. Focus on credit cards and personal loans first.
Make a payoff plan. List debts by interest rate, attack the highest first while paying minimums on the rest.
Entering retirement debt free, or close to it, gives you breathing room. For extra income ideas, read our guide to starting a business at 40.
Debt payoff order
Build Multiple Income Streams
Do not rely on one source.

In retirement, income can come from savings, Social Security, part time work, rental income, or a small business. The more streams, the more secure.
Start building now. A side hustle in your 40s can become retirement income later.
Diversification is not just for investments. It is for income too. Explore these career change ideas.
Understand Social Security Benefits
Know what to expect.

Create an account at ssa.gov to see your estimated benefits. Check your earnings record for errors.
Delaying benefits past full retirement age increases your monthly check. Each year you wait up to 70 adds about 8 percent.
Understand your options now so you can plan around them.
Check your statement yearly.
Learn your full retirement age.
Model early vs late claiming.
Create a Healthcare Cost Plan
Healthcare is a big retirement expense.

Medicare starts at 65, but it does not cover everything. Budget for premiums, copays, and prescriptions.
Consider a Health Savings Account if you are eligible. Contributions are tax deductible and withdrawals for medical costs are tax free.
Planning for healthcare now prevents nasty surprises later.
Open an HSA if eligible.
Budget for Medicare gaps.
Assuming Medicare covers all.
Ignoring prescription costs.
Downsize or Relocate Strategically
Housing is your biggest cost.
A smaller home means lower mortgage, taxes, insurance, and upkeep. Moving to a lower cost area can stretch savings further.
You do not have to decide now. But start thinking about what you want. Do you want to stay near family or try somewhere new?
Strategic moves in your 50s can set up a comfortable retirement.
| Option | Benefit |
|---|---|
| Downsize | Lower monthly costs |
| Relocate | Stretch savings further |
Invest for Growth With Age Appropriate Risk
You still need growth in your 40s.
With 20 plus years until retirement, you can handle market ups and downs. Being too conservative now can hurt more than help.
A mix of stocks and bonds that fits your comfort level is key. Rebalance yearly to stay on track.
Do not try to time the market. Steady investing wins over time.
Time in the market beats timing the market.
Build an Emergency Buffer Separate From Retirement
Do not raid retirement for emergencies.

Keep 3 to 6 months of expenses in a separate high yield savings account. This protects your retirement accounts from early withdrawals and penalties.
Emergencies will happen. A buffer keeps them from derailing your future.
Fund this before increasing retirement contributions beyond the employer match.
📌 Good To Know
Early 401k withdrawals usually face taxes plus a 10 percent penalty. An emergency buffer helps you avoid that.
Plan for Long Term Care Costs
This is the expense people forget.
Long term care can cost tens of thousands per year. Medicare covers very little of it.
Look into long term care insurance in your 40s or 50s when premiums are lower. Or plan how you would self fund.
Having the conversation with family now is a gift to everyone.
Review and Update Beneficiaries
Small detail, big impact.

Beneficiary designations on retirement accounts and insurance override your will. If they are outdated, the wrong person could inherit.
Review them after big life events like marriage, divorce, births, or deaths. It takes 10 minutes.
This simple check protects the people you love.
Check these accounts
Create a Retirement Budget That Reflects Real Life
Dream, then do the math.
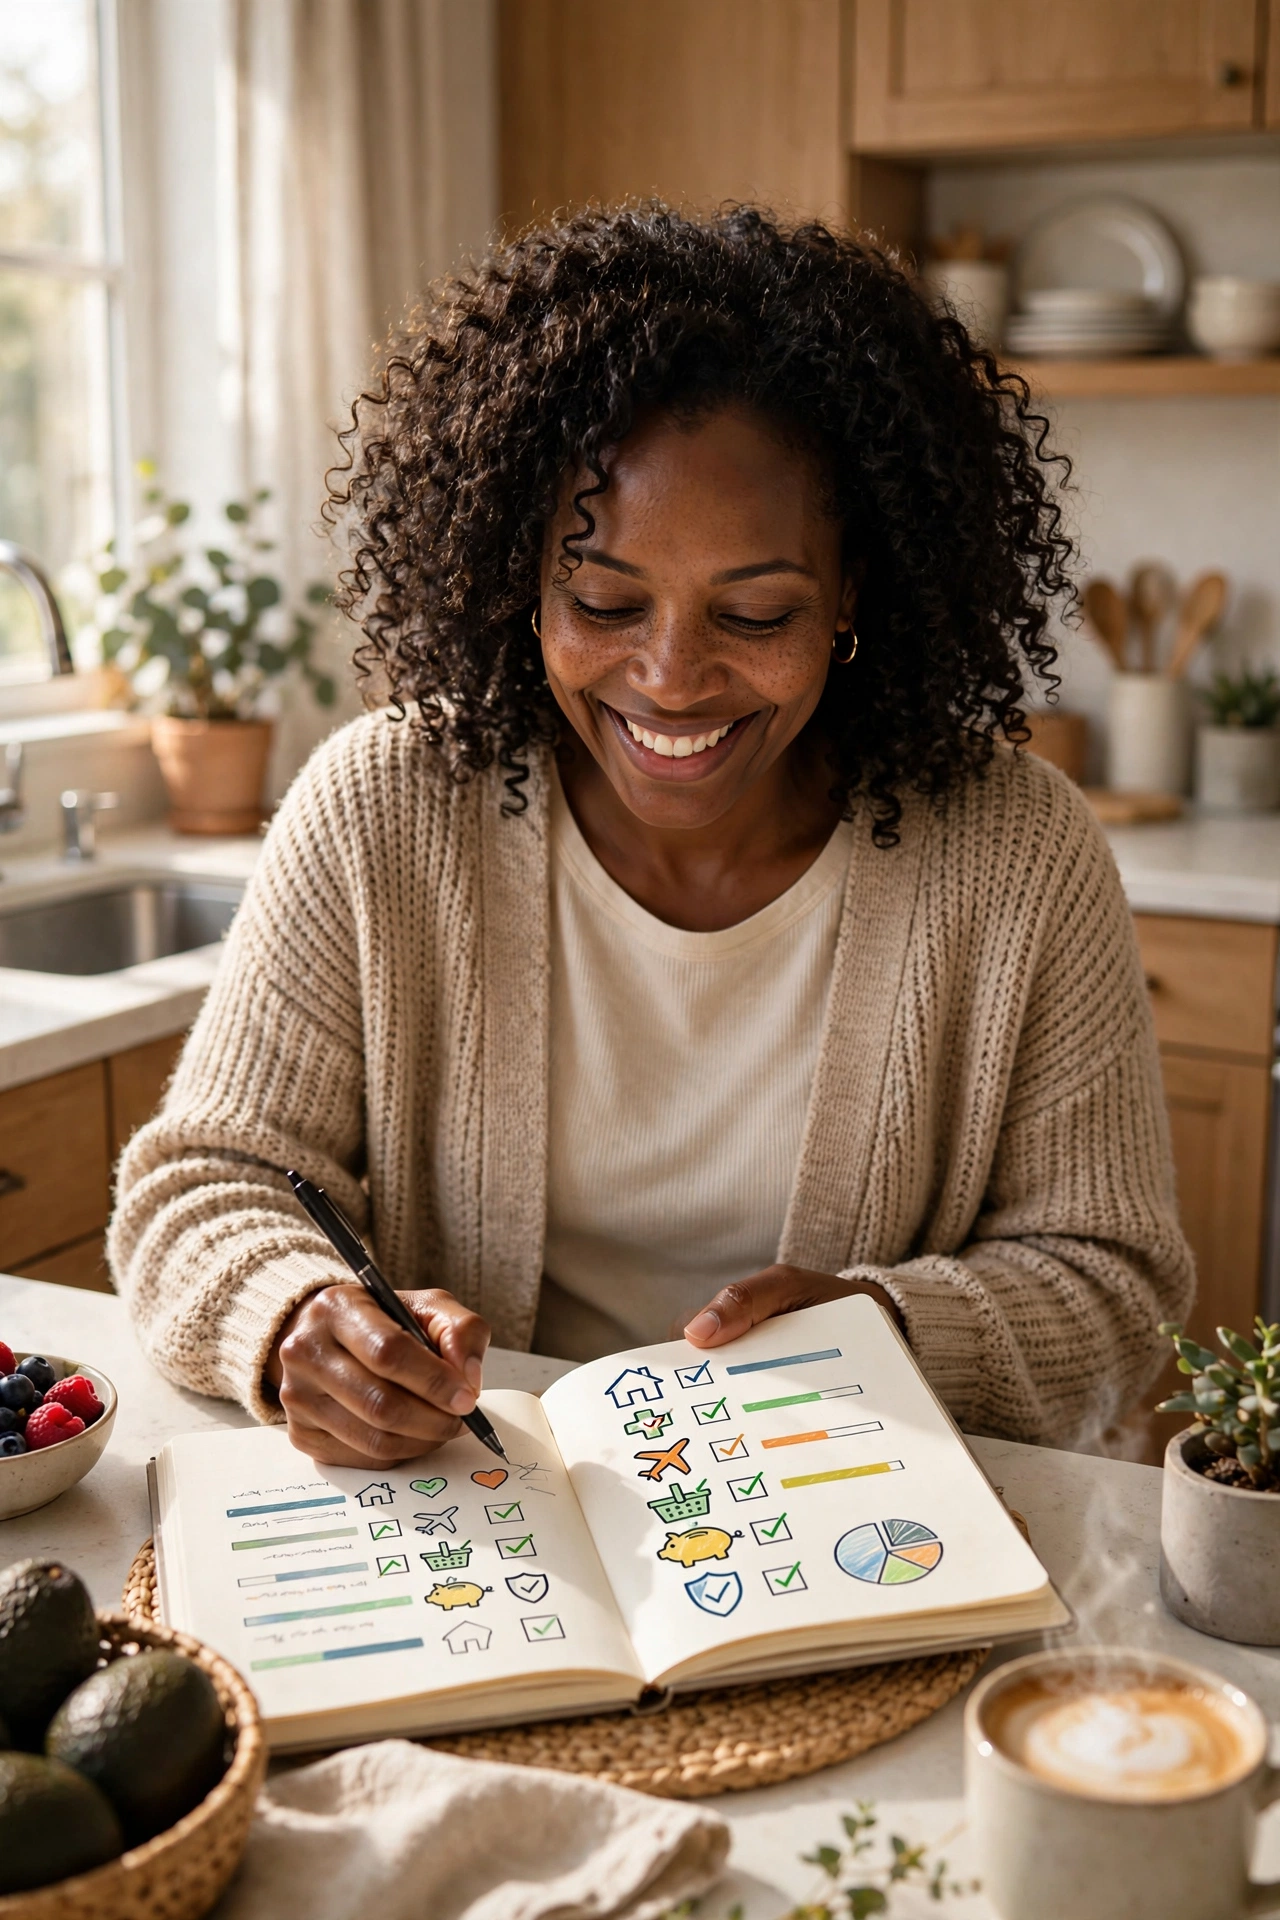
Write down what you want retirement to look like. Travel, hobbies, helping family, then price it out.
Compare that to your projected income. If there is a gap, you have time to close it.
A realistic budget turns vague hopes into a real plan. Protect your budget with a steady morning routine.
Consider Part Time Work You Enjoy
Retirement does not have to be all or nothing.
Many women find a gradual transition works best. Part time consulting, teaching, or a passion project keeps income flowing and minds sharp.
It also lets your savings grow longer before you draw from them.
Think about what you would love doing 10 to 15 hours a week. Start building toward it now.
List skills you enjoy using.
Test it as a side project now.
Scale it when you are ready.
Get Professional Advice You Can Trust
You do not have to do this alone.
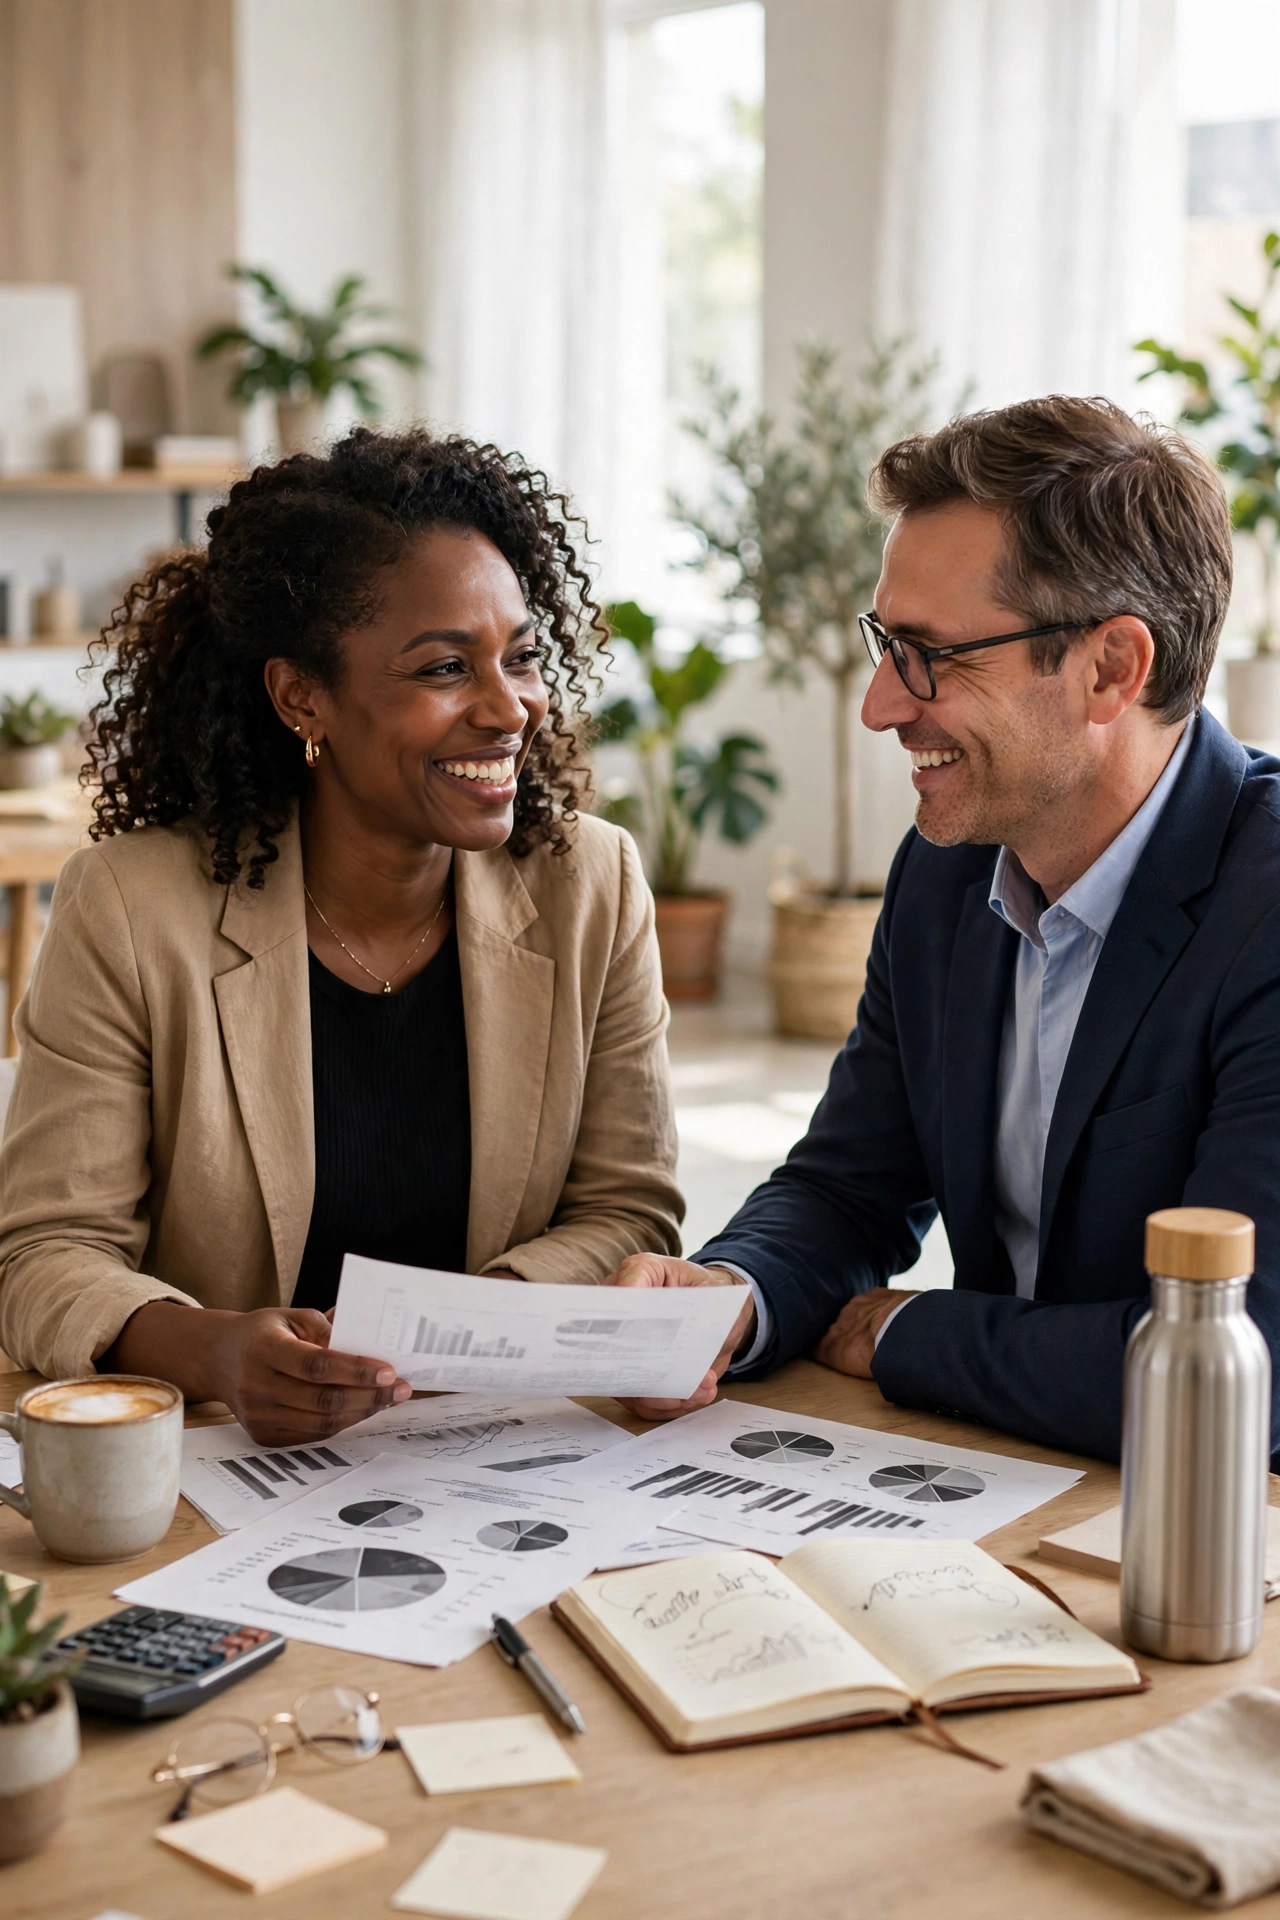
A fee only financial planner can review your full picture and spot gaps. Look for a fiduciary, someone legally required to act in your best interest.
One planning session in your 40s can be worth thousands later. Ask friends for referrals or search professional directories.
Good advice pays for itself.
Choose a fee only fiduciary.
Ask about their experience.
Advisors paid by commission only.
Anyone promising guaranteed returns.
Conclusion
Retirement planning for Black women over 40 is about taking steady, smart steps now. You do not need to have it all figured out today. Start with one or two moves from this list. If you want a bigger fresh start, see our guide to reinventing yourself after 40.
The best time to start was years ago. The second best time is right now. Your 40s give you time, earning power, and wisdom, use all three.
Pick your first step today. Your future self will be so glad you did.